

© 2026 - All Rights Reserved - (See www.equoria.io for more information)
Residential real estate is one of the most foundational and widely held asset classes in the global economy. Single-family homes, condominiums, and small multifamily properties form the backbone of household wealth, long-term savings, and intergenerational asset transfer. Historically, however, participation in residential real estate ownership has required substantial upfront capital, strong credit profiles, and long-term debt obligations—placing direct ownership out of reach for large segments of the population.
Residential real estate equity financing offers an alternative path. Rather than relying exclusively on traditional mortgage debt, equity financing enables homeowners, buyers, developers, or sponsors to raise capital by selling a portion of ownership in a residential property to equity investors. These investors contribute capital in exchange for a defined equity interest and the right to participate in future economic outcomes tied to the property.
For homeowners and residential developers, equity financing can unlock capital without increasing debt burdens. For investors, it offers exposure to residential real estate equity—often considered a stable, inflation- resilient asset—without the responsibilities of direct ownership or property management.
This post provides a comprehensive examination of residential real estate equity financing, how it works, how it compares to debt financing, its advantages and disadvantages, the major equity structures in use today, and the legal, tax, and market considerations that shape its adoption.
How Does Residential Equity Financing Work?
Residential equity financing aligns the financial interests of property owners and equity investors by sharing ownership risk and reward. Instead of borrowing funds that must be repaid with interest, the property owner grants an ownership stake tied to future property value, income, or both.
Simplified Example
A homeowner or residential developer owns or acquires a $500,000 single- family home.
The owner contributes $100,000 of personal capital.
Equity investors contribute $100,000 in exchange for a 20%
ownership interest.
The remaining capital structure may include mortgage debt or additional equity.
If the property generates rental income, appreciation, or is sold in the future, proceeds are distributed according to ownership percentages, subject to the governing equity agreement.
If the home is later sold for $650,000, the equity investors receive 20% of the net sale proceeds after transaction costs. If the property underperforms, equity investors share in that downside rather than receiving fixed payments.
This structure reduces leverage-related risk for the homeowner while giving investors direct participation in residential real estate outcomes.
Residential Equity Financing vs. Mortgage Debt Financing
Residential equity financing differs materially from traditional mortgage lending. While debt remains the dominant financing mechanism for residential properties, equity structures introduce flexibility and risk- sharing not available through loans.
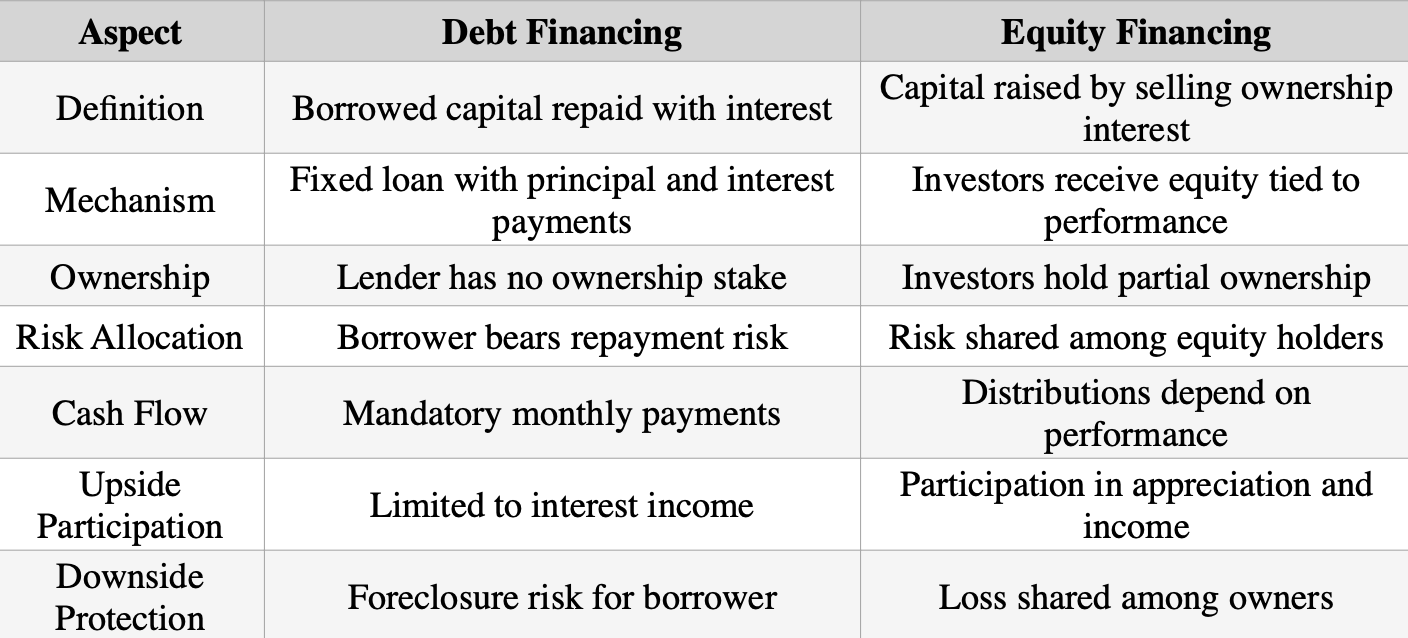
Equity financing can be particularly attractive when interest rates are high, credit is constrained, or borrowers seek to reduce monthly obligations and financial stress.
Pros and Cons of Residential Equity Financing
Like all financing strategies, residential equity financing carries tradeoffs that must be carefully evaluated.
Advantages
No Mandatory Repayment – Equity capital does not require monthly
payments, reducing cash flow strain.
Shared Risk – Investors share in both upside and downside, lowering personal financial exposure.
Improved Affordability – Equity contributions can reduce required mortgage size or down payment.
Access to Capital – Enables participation for buyers or owners who may not qualify for additional debt.
Long-Term Alignment – Investors are incentivized to support property value growth.
Disadvantages
Ownership Dilution – Property owners give up a portion of future
appreciation.
Profit Sharing – Sale proceeds or income must be shared with equity investors.
Reduced Control – Some equity structures grant investors limited governance rights.
Complex Structuring – Legal documentation and compliance requirements can be significant.
Exit Considerations – Equity investors will eventually seek liquidity, requiring sale, refinancing, or secondary transfer.
Understanding these dynamics is essential before choosing equity financing for residential properties.
Types of Residential Real Estate Equity Financing
Residential equity financing exists in several forms, each designed to meet different capital needs and investor profiles.
Traditional Home Equity Loans (not available on Equoria platform)
Borrowing against existing equity via a second mortgage. While technically debt, these loans are often compared to equity structures.
Cash-Out Refinancing (not available on Equoria platform)
Replacing an existing mortgage with a larger loan and extracting equity as cash. Increases leverage and debt service.
Home Equity Lines of Credit - HELOCs (not available on Equoria platform)
Revolving credit lines secured by home equity, typically used for short- term liquidity needs.
Co-Equity Agreements
Investors contribute capital in exchange for a percentage of future appreciation or sale proceeds, without monthly payments.
Residential Crowdfunding
Platforms pool capital from many investors to fund residential properties, offering fractional equity interests.
Additional Considerations in Residential Equity Financing
Evaluating Investor Alignment
Investor objectives must align with property owner goals. Misalignment around time horizon, exit strategy, or risk tolerance can create conflict.
Legal and Regulatory Compliance
Residential equity financing may implicate securities laws, consumer protection regulations, and state-specific property rules. Clear disclosures, properly structured agreements, and experienced legal counsel are essential.
Tax Implications
Equity financing affects taxation differently than debt. Investors may benefit from capital gains treatment and depreciation pass-throughs, while owners forego interest deductions. Tax planning is critical for all parties.
Market Conditions
Housing prices, interest rates, employment trends, and regional supply- demand dynamics influence equity outcomes. Equity financing can be particularly attractive during periods of high mortgage rates or affordability constraints.
Conclusion
Residential real estate equity financing represents a powerful and increasingly relevant alternative to traditional mortgage debt. By allowing property owners and investors to share risk, capital, and long- term value creation, equity financing expands access to residential real estate participation while reducing reliance on leverage.
For homeowners, buyers, and developers, it offers flexibility and affordability. For investors, it provides exposure to one of the most stable asset classes without the burdens of direct ownership. As housing affordability challenges persist and technology continues to lower barriers to participation, residential equity financing is positioned to play a growing role in the future of real estate markets.
When thoughtfully structured—with careful attention to legal, tax, and market considerations—residential equity financing can unlock new pathways to ownership, investment, and long-term wealth creation.